Strategy vs. CleanSpark: Which Bitcoin Stock Has Greater Upside Now?
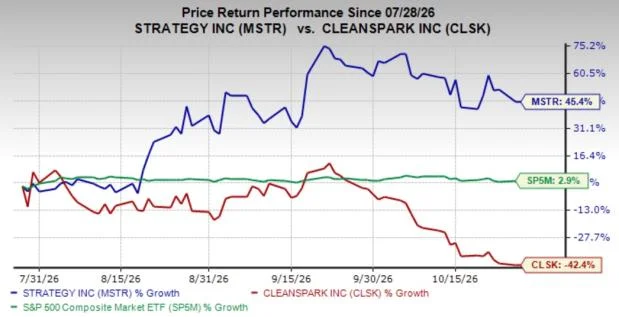
Bitcoin's reach now extends well beyond cryptocurrency exchanges. Companies owning Bitcoin or supporting its network offer investors different ways to participate in Bitcoin price movements. Strategy MSTR and CleanSpark CLSK share a clear connection to Bitcoin, making both sensitive to changes in the digital asset's value, investor sentiment and access to financing.Their approaches, however, differ. Strategy has made Bitcoin accumulation the center of its financial strategy, using capital markets to build a large corporate treasury while maintaining an enterprise software business. CleanSpark earns revenues by mining new Bitcoin, operating energy-intensive facilities and increasingly developing infrastructure for artificial intelligence workloads.This creates two distinct sources of opportunity and risk. Strategy depends heavily on Bitcoin prices and its ability to manage capital efficiently. CleanSpark must contend with mining costs while converting new data center projects into dependable cash flows. Comparing these paths helps clarify what could drive each stock next.The Case for MSTRStrategy offers a relatively direct way to gain corporate exposure to Bitcoin without relying on the economics of running mining facilities. Its holdings reached 848,517 Bitcoin as of Oct. 18, giving the company a scale that CleanSpark's treasury cannot approach. A sustained recovery in Bitcoin could lift the value of this reserve and improve investor confidence in MSTR.Another advantage is Strategy's established access to financing. It can raise funds through common shares and preferred securities, pursue Bitcoin purchases or manage existing obligations. Its expanding digital credit business provides more options than the operating cash flows available to a typical miner. This flexibility matters when market conditions change quickly.The company has also worked to protect liquidity. Its dollar reserve stood at about $4.83 billion, supporting preferred dividends and debt interest. Strategy repurchased $193 million of STRC shares and expanded its digital credit repurchase authorization to $3 billion, demonstrating active management of financing costs and obligations.Still, these strengths come with risks. Issuing common shares can dilute investors, while preferred dividends create recurring commitments. Strategy's second quarter included a large noncash Bitcoin valuation loss, showing how sharply reported earnings can swing. Its software operations offer diversification but remain secondary to the treasury strategy.Compared with CleanSpark, Strategy avoids direct exposure to mining equipment replacement, electricity costs and construction schedules. Its future remains closely tied to Bitcoin, yet its treasury scale and financing flexibility provide a stronger foundation for investors willing to accept substantial volatility and prolonged drawdowns.The Case for CLSKCleanSpark has built a Bitcoin mining network, but scale may not translate into stronger shareholder returns. In September, CleanSpark reported 50 exahashes per second of operational capacity and produced 529 Bitcoin. Mining remains sensitive to electricity prices, network difficulty and equipment efficiency, factors Strategy avoids through its treasury-focused model.That pressure is visible. CleanSpark's fiscal third-quarter revenues declined 30.5% year over year, while its gross margin slipped sequentially. A large net loss reflected Bitcoin valuation changes as well as the difficult backdrop. Larger fleets alone may not offset weaker mining economics.Its shift toward artificial intelligence infrastructure offers an alternative. Its Sandersville project has a 20-year lease representing about $6.6 billion in contracted revenues. CleanSpark also closed $2.276 billion of secured notes carrying a 7.875% rate, which management says fully funds construction. These are meaningful achievements, but contracted revenues are not immediate cash flow. Initial delivery is expected in late 2027.Expansion in Texas adds another layer of uncertainty. It has an exclusivity arrangement covering up to 885 megawatts, not a signed long-term lease for those sites. Conditional grid classifications represent progress, but final development, customer commitments and project execution still matter. Financing costs could weigh on returns if schedules slip.CleanSpark ended September with 13,530 Bitcoin, including holdings committed to collateral arrangements. Unlike Strategy, it must keep investing in physical capacity while navigating a changing business model. Until new infrastructure delivers recurring income and mining profitability improves, its apparent growth opportunities carry considerable execution risk.How Do Estimates Compare for MSTR & CLSK?The Zacks Consensus Estimate for MSTR’s 2026 and 2027 sales calls for year-over-year growth of 5.51% and 1.70%, respectively. Over the past 30 days, earnings estimates for 2026 have improved, while those for 2027 have declined.For MSTR:The Zacks Consensus Estimate for CLSK’s fiscal 2026 and 2027 sales implies a year-over-year decline of 23.77% and growth of just 0.80%, respectively. The consensus mark for CLSK’s fiscal 2026 and 2027 earnings has been revised southward in the past 30 days.For CLSK:Price Performance and Valuation of MSTR & CLSKOver the past three months, MSTR shares have surged 45.4%, while CLSK shares have plunged 42.4%. In comparison, the S&P 500 composite has advanced 2.9% in the same time frame.Valuation-wise, none of the stocks look attractive. Both MSTR and CLSK have a Value Score of F.ConclusionBoth stocks could rebound sharply if Bitcoin strengthens, and neither offers a defensive investment profile. However, their paths to improved shareholder returns look different. Strategy already controls a much larger Bitcoin reserve and can use established capital market channels to manage its holdings. The risks of dilution and preferred dividends deserve attention, especially during extended downturns. CleanSpark has a genuine opportunity in data centers, but its mining pressures and long construction schedule leave more results to prove. For investors deciding where to maintain Bitcoin-related equity exposure, MSTR looks more defensible while reducing exposure to CLSK appears prudent for now.While MSTR carries a Zacks Rank #3 (Hold), CLSK has a Zacks Rank #4 (Sell).You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.Radical New Technology Could Hand Investors Huge GainsQuantum Computing is the next technological revolution, and it could be even more advanced than AI.While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power.Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free reportStrategy Inc (MSTR): Free Stock Analysis ReportCleanspark, Inc. (CLSK): Free Stock Analysis ReportThis article originally published on Zacks Investment Research (zacks.com).Zacks Investment Research